The Strait of Hormuz has never had to be sealed shut to rattle the global economy; it only has to become dangerous enough that insurers, shippers, and traders start pricing in catastrophe, and that threshold has now been crossed repeatedly since early 2026.
Key Points
- Tanker attacks in the Strait of Hormuz hit a wartime high in early October 2026, with traffic falling to its lowest level in more than two months even as Iran insisted it retained control of the waterway.
- The International Energy Agency called the resulting disruption the largest in the history of global energy markets and coordinated a 400-million-barrel emergency stock release at the conflict’s worst point.
- Despite the attacks, Gulf oil exports recovered to above 80% of pre-war levels on several occasions, as shippers rerouted, escorted convoys, and leaned on pipeline bypasses.
- The gap between “control” and “disruption” is the whole story: Iran can make the Strait lethal without closing it, and that distinction, not a binary open-or-shut outcome, is what moves oil prices.
- The 1980s Tanker War offers the closest precedent — sustained attacks on merchant shipping that never produced a permanent shutdown, a pattern now repeating at a larger and more technologically mediated scale.
A Chokepoint Under Siege, Not Under Lock
The Strait of Hormuz carries roughly a fifth of the world’s petroleum liquids on an ordinary day, a volume with essentially no substitute route for most of the producers that depend on it. Only Saudi Arabia and the United Arab Emirates operate pipelines capable of bypassing the Strait entirely, and even those have finite capacity. That geography is why a relatively modest shift in transit risk there produces an outsized reaction in Brent futures. Since late February 2026, when U.S. and Israeli operations against Iran escalated, Tehran has tried to translate that geographic leverage into a bargaining chip, attempting to redirect commercial vessels into its territorial waters and striking ships that refused to comply.
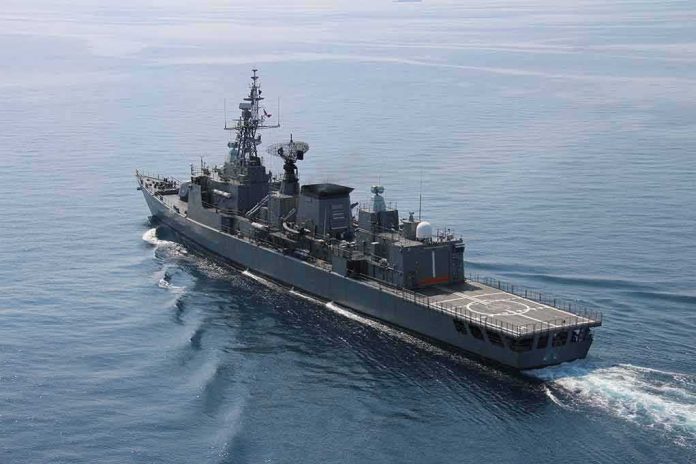
Those attacks are not abstract. Iran’s naval forces have publicly claimed credit for specific strikes, describing vessels as having used “unauthorised” routes through the Strait’s southern section — language used, for instance, around the targeting of the tanker MV Sun Shine’s engine room and propulsion system. By early October, UKMTO and commercial trackers were logging roughly one attack a day in the Strait or the adjoining Gulf of Aden, and weekly tanker-strike counts reached ten, a wartime record that pushed crossings down to as few as seven vessels on the worst days — the slowest pace since late July.
How Markets Priced the Danger
Brent crude responded exactly as chokepoint economics would predict, jumping more than 5% intraday to roughly $105 a barrel as the attack tempo rose. That price move reflected more than headline fear. Kpler data showed crude flows through Hormuz falling 27% from the prior wartime peak to about 10.1 million barrels a day, roughly three-quarters of pre-war volume, and freight costs for a very large crude carrier sailing from the Gulf to China climbed to the equivalent of $24 a barrel — freight alone consuming a quarter of the cargo’s value. At the disruption’s most acute phase, the IEA described it as the largest supply disruption in the history of energy markets and coordinated a 400-million-barrel emergency stock release among member countries to cushion the blow.
Why the Strait Never Actually Closed
Here the record complicates any claim that Iran achieved operational control. Weeks after the emergency release, IEA Executive Director Fatih Birol said there was “plenty of oil in the market” and no plan for another coordinated action, a judgment that would have been untenable had Hormuz truly gone dark. Reuters’ review of Kpler data found regional crude exports exceeding pre-war levels on several days in late September, with the seven-day moving average reaching 18.5 million barrels a day by October 1. Al Jazeera’s reporting put Gulf flows, excluding Iran itself, at more than 81% of pre-war levels that same month. Exporters adapted around the danger rather than halting in the face of it: Gulf of Oman and Red Sea routes picked up an estimated 6.7 million barrels a day in compensating volume, while tankers increasingly transited at night with transponders switched off, under escort, in convoys resembling wartime shipping practice more than routine commerce.
That adaptation came at real cost — tanker shortages, ship-to-ship transfers to mask origin, insurance premiums that priced risk directly into freight rates — but it is adaptation nonetheless, and it is the reason Hormuz has functioned as a site of sustained disruption rather than outright closure. The distinction matters enormously for how policymakers and markets should read the next escalation: a state does not need to hold a waterway to wound the ships that cross it.
The Precedent That Still Teaches the Clearest Lesson
This is not the first time a hostile power has tried to weaponize Hormuz without closing it. During the Iran–Iraq Tanker War of the 1980s, both belligerents attacked merchant shipping tied to the opposing war effort, damaging or destroying more than 500 vessels and killing over 400 civilian seamen in what became the most sustained assault on merchant shipping since the Second World War. Yet that campaign never produced a durable shutdown of the Strait or a lasting collapse in Gulf exports — shipping adapted, escorts multiplied, and trade continued under fire. The current conflict differs mainly in scale and instrumentation: satellite tracking, autonomous vessels, and real-time freight-rate markets now make the costs of disruption visible almost instantly, but the underlying dynamic — danger without closure — is the same one that defined the Gulf four decades ago.
While Trump brings Russian diesel into the US, a tanker carrying 750,000 barrels of oil has struck a sea mine in the Strait of Hormuz.
As a reminder: according to Trump, oil prices are determined by Ukrainian attacks on Russian refineries, while the pic.twitter.com/bv75uX3vQs
— QThestorm RV🦅🇺🇲 (@17QStorm6RV) October 12, 2026
What This Means for the Next Flare-Up
The durable lesson for anyone trying to read oil markets through a Middle East crisis is to stop treating “is the Strait open or closed” as the operative question. It rarely is fully either. The more useful questions are how much risk premium freight and insurance markets are absorbing, how much volume is shifting to alternate routes and pipelines, and whether a coordinating body like the IEA judges the global cushion — strategic reserves, spare production capacity, substitute flows — sufficient to avoid another emergency release. Those indicators moved independently of the attack headlines throughout 2026, and they will again the next time a tanker takes fire in the Strait of Hormuz.
Sources:
cnbc.com, euronews.com, thenationalnews.com, aljazeera.com, reuters.com, iea.org, edition.cnn.com, businessday.ng, iranintl.com, rnz.co.nz, eia.gov, time.com